ความแตกต่างระหว่างมาตรฐาน TFRS PAEs กับ NPAEs

The difference between TFRS PAEs and NPAEs standards

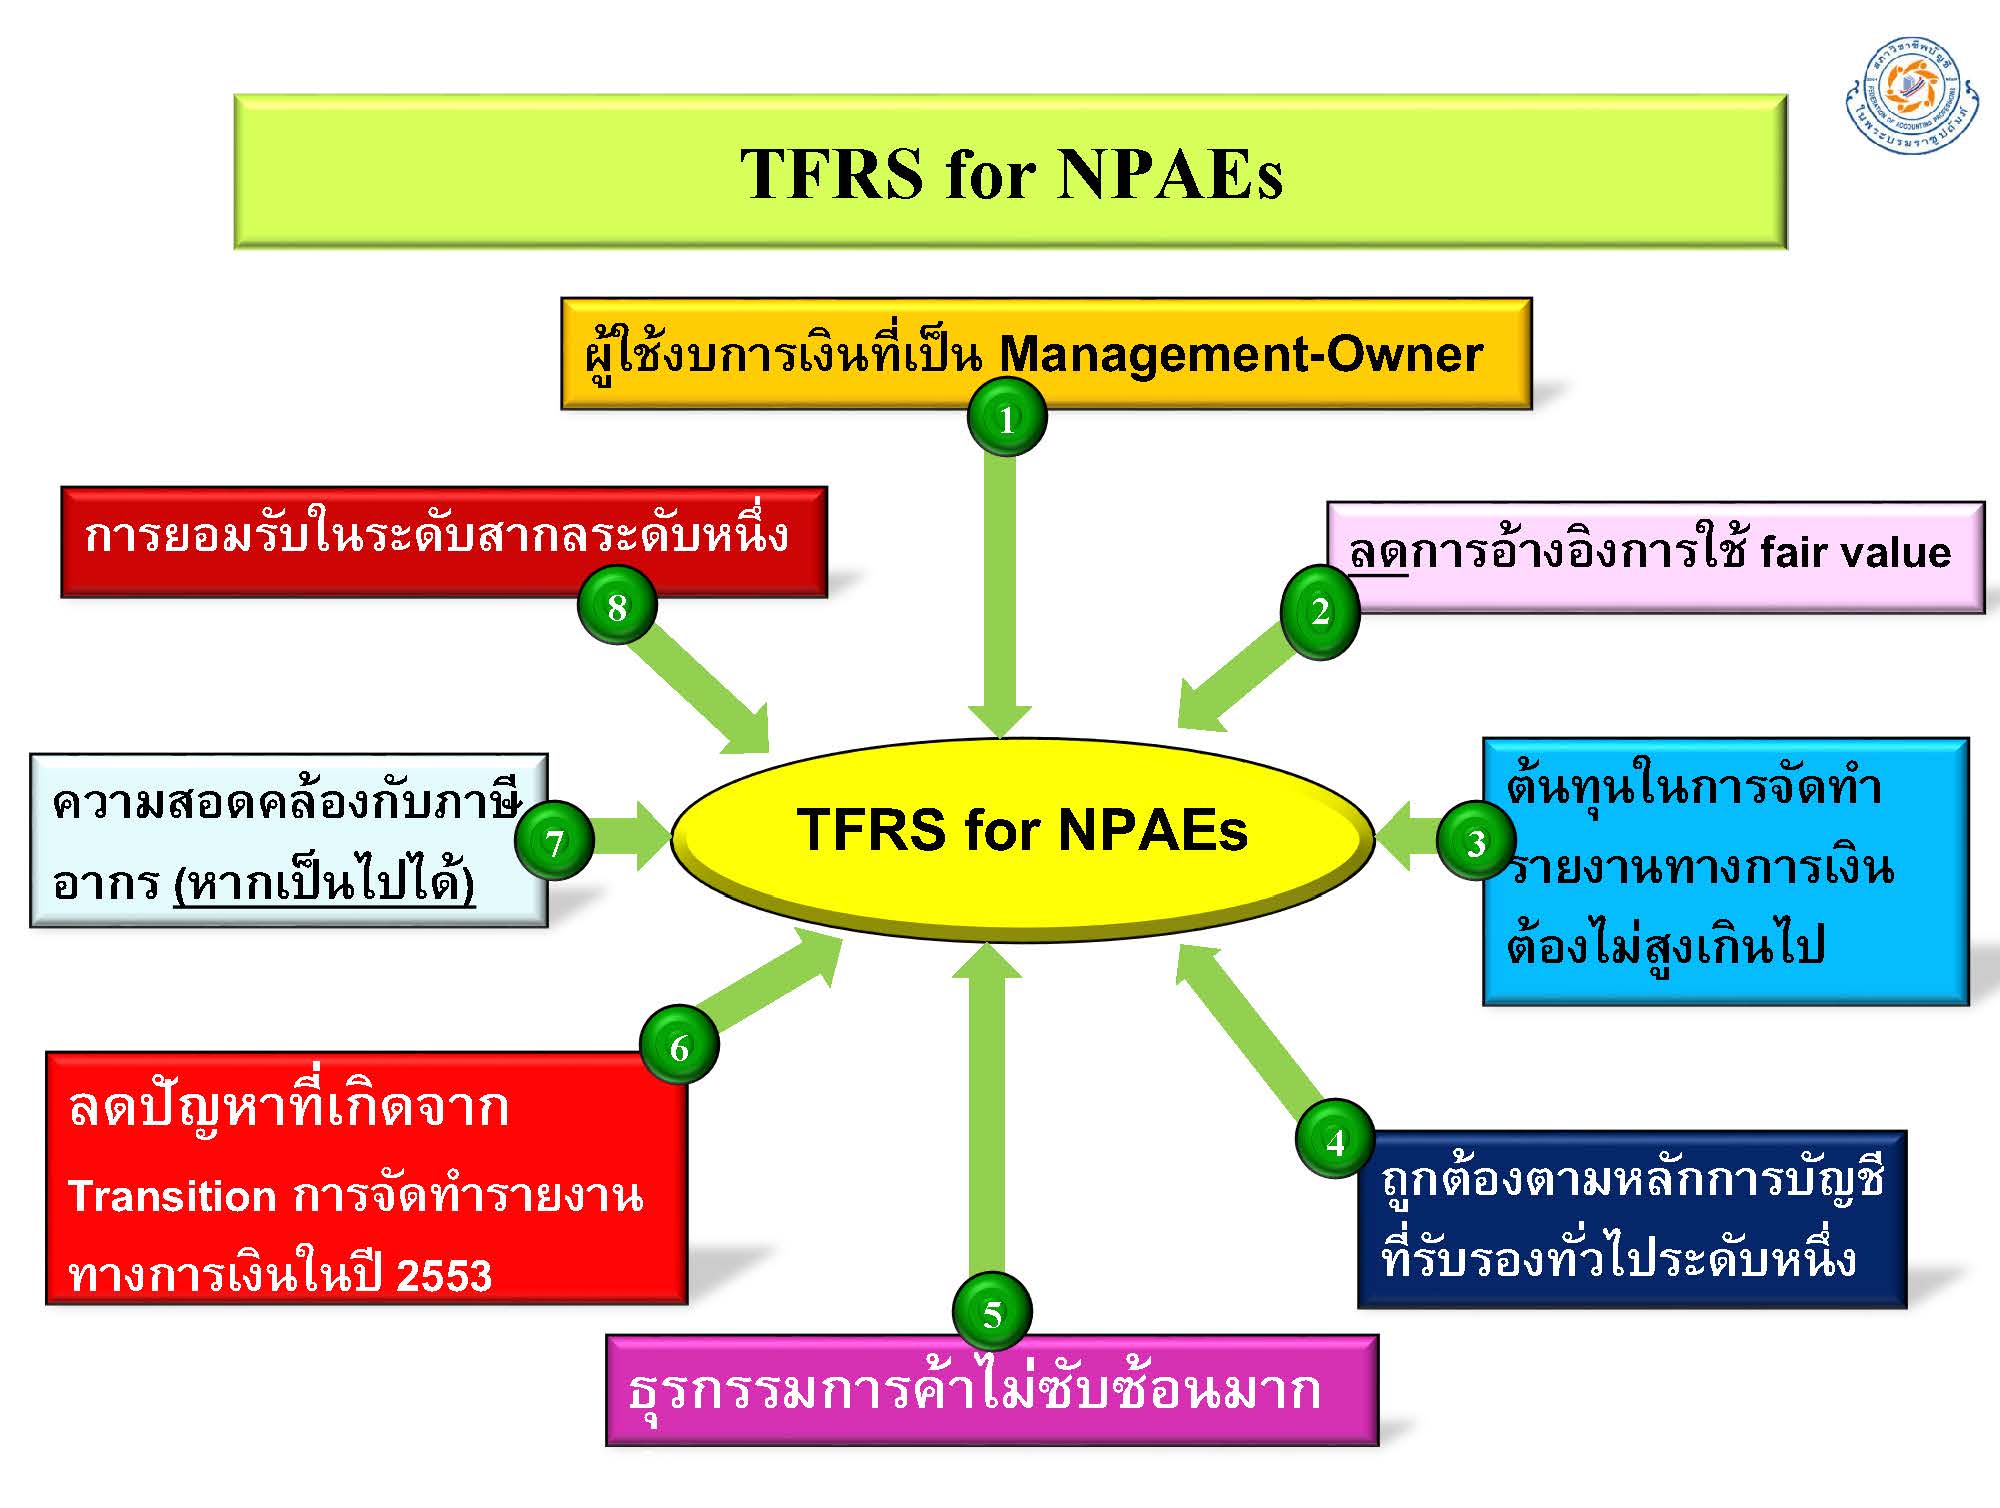
          Before we delve into PAEs and NPAEs, let’s get acquainted with the financial reporting standards in Thailand. Thailand has its own set of financial reporting standards called Thai Financial Reporting Standards (TFRSs), which are based on the International Financial Reporting Standards (IFRSs) to ensure international acceptance. These financial reporting standards apply to legal entities responsible for accounting in accordance with the Accounting Act of 2000. This includes registered companies trading in the stock market as well as general entities outside the stock market. However, while the international financial reporting standards are intended for publicly accountable entities (PAEs) and involve complex requirements, such as the use of fair value as a basis for financial reporting, they impose additional costs on the financial reporting process for non-publicly accountable entities (NPAEs). NPAEs primarily consist of medium-sized and small-scale businesses.

Publicly Accountable Entities | PAEs

          Publicly Accountable Entities (PAEs) refer to businesses that fall into the following categories :

  1. Businesses with equity or debt securities traded in the public market.
  2. Businesses that submit or are in the process of submitting financial statements to the Securities and Exchange Commission (SEC) or regulatory bodies for the purpose of issuing securities in the public market. This includes businesses engaged in primary financial activities and the management of assets owned by a wide range of external individuals or entities, such as financial institutions, life insurance companies, non-life insurance companies, mutual fund management companies, and commodity futures exchanges in Thailand.
  3. Public companies.
  4. Other entities as determined and specified, which are required to prepare financial statements using the comprehensive set of accounting standards (TFRS (2009)). This set includes accounting standards such as TAS 32 (TFRS 4), TIC 4, and TFRIC 1.
Publicly Accountable Entities | PAEs

Non-Publicly Accountable Entities | NPAEs

          Non-Publicly Accountable Entities (NPAEs) refer to entities that are not PAEs and may prepare financial statements using either the small set of accounting standards (TFRS for NPAEs (2011)) or the comprehensive set of accounting standards if they do not wish to adopt the TFRS for NPAEs.

Non-Publicly Accountable Entities | NPAEs

The difference between TFRS for PAEs and NPAEs standards.

 
PAEs
NPAEs
Financial Statements
– Comprehensive Income Statement
– Profit and Loss Statement (P&L)
– Cash Flow Statement
– statement of comprehensive income (non-disclosure of specific expenses).
– statement of financial position (3-period balance sheet)
 
–income statement (mandatory disclosure of significant expenses and additional disclosure of expenses by nature).
 
Investment capital
– cost of sales
– cost deducted by provision for depreciation
–fair value (trading/securities held for sale).
– fair value adjustments through profit or loss and other comprehensive income.
Investment in subsidiaries.
– Financial statements must be prepared and recognition of profit/loss must be in accordance with the revenue and expense recognition principles.
–No need to prepare consolidated financial statements and record cost prices.
Employee benefits.
– Calculation must be based on actuarial mathematics standards.
– Calculate using an estimation method, which the Auditor deems reasonable.
Intangible Assets
– No need for disposal (similar to depreciation calculation), by examining whether there is impairment at the end of the year or not.
– Disposal after 10 years.
Recognize revenue.
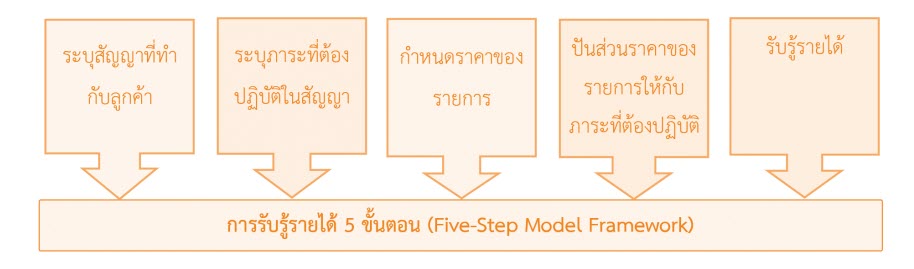
– According to TFRS 15’s 5-step process.
– Recognize revenue when control is transferred or at a point where risks and rewards are transferred and revenue is recognized.
Income from real estate sales
– Revenue is recognized upon transfer.
– Can choose 3 Options
 
1. Receiving income upon transfer
 
2. Understanding income based on the proportion of successfully completed work
 
3. Understanding income based on installment payments transferred when due
Income TAX
–Calculating deferred tax assets due to differences between accounting and tax, which may result in assets/liabilities, income tax, or deferred tax assets (DTA)/deferred tax liabilities (DTL).
– No need to calculate, just record the accrued Income TAX.

According to TFRS 15's 5-step process.

(Five-step Model Framework

          Business owners, executives, and accounting managers who are interested in financial statement audit services or accounting consulting services, whether for industrial manufacturing groups, factory groups, or those interested in having our company conduct inventory counts or ending inventory audits, financial statement closing services, accounting audit services, audit services, or financial statement audits, please feel free to contact our audit firm through the contact channels below.

         ✅ โทร 📞 02-114-7715
         ✅ Web 🌐 https://www.accconsultingservice.com/
         ✅ Inbox 📩 http://m.me/100581915340875
         ✅ Line 📱 https://lin.ee/PhD3G7F
         ✅ Mail 📧 [email protected]
Facebook
Twitter
Pinterest

ความรู้/ข่าวสารที่คุณอาจสนใจ

Year-End Tax Planning for Companies in Thailand: A Practical Checklist

Corporate Tax · by ACC Consulting Year-End Tax Planning for Companies in Thailand Doing tax right is the smartest way to save — a practical checklist before your fiscal year-end Written and reviewed by the accounting & tax specialists at ACC Consulting Co., Ltd. Year-end tax planning in Thailand is where well-run companies lock in legitimate savings — before the books close, not after. For a company with a December fiscal year-end, the weeks leading up to 31 December are the last chance to capture deductions, use incentives and get the structure right. This guide is a practical checklist for Thai and foreign-owned companies, built on one principle: the smartest way to save tax is to be correctly inside the system. Year-end tax planning in Thailand: the short answer Before your fiscal year closes, forecast your taxable profit, make sure every deductible expense is captured with proper documentation, use any incentives and allowances you qualify for, reconcile your VAT and withholding tax, and — for BOI companies — confirm you are meeting promotion conditions. Acting before year-end is what turns

อ่านต่อ »
corporate income tax in Thailand

Corporate Income Tax in Thailand: A Guide for Foreign Investor

Corporate Tax · by ACC Consulting Corporate Income Tax in Thailand: A Guide for Foreign Investors How companies are taxed on profit — rates, filing and reliefs, explained simply Written and reviewed by the accounting & tax specialists at ACC Consulting Co., Ltd. Corporate income tax in Thailand is the tax a company pays on its net profit — and for foreign investors, understanding it early prevents costly surprises. Whether you run a Thai-incorporated subsidiary, a branch of an overseas parent, or a BOI-promoted company, the rates and filing rules are broadly the same, with a few important nuances for cross-border income. This guide covers the essentials, on the principle that being correctly in the system is the smartest way to save. Corporate income tax in Thailand: the essentials A company incorporated in Thailand pays corporate income tax (CIT) on its worldwide net profit, while a foreign company carrying on business in Thailand (for example through a branch) pays on its Thai-source net profit. The standard rate is 20%, with lower graduated rates for qualifying SMEs. CIT is filed twice

อ่านต่อ »
BOI

Foreign Company Tax in Thailand: BOI, Setup & Compliance Guide

Foreign Business & BOI · by ACC Consulting Tax & Accounting for Foreign-Owned and BOI Companies in Thailand Doing tax right is the smartest way to save — a practical guide for foreign investors Written and reviewed by the accounting & tax specialists at ACC Consulting Co., Ltd. Foreign company tax in Thailand is often simpler than investors fear — provided the company is set up and run correctly inside the system. Foreign-owned and BOI-promoted companies can enjoy real advantages, from tax holidays to 100% ownership, but those benefits depend on proper registration, accounting and filing. This guide explains how foreign companies are taxed, the ownership routes available, the main BOI privileges, and the compliance that protects them. Foreign company tax in Thailand: the short answer A company incorporated in Thailand — even if foreign-owned — is a Thai taxpayer. It pays corporate income tax (CIT) on its net profit, generally at 20% (with graduated SME rates for qualifying companies), charges 7% VAT once registered, and withholds tax on certain payments. BOI-promoted companies may enjoy CIT exemptions on top of

อ่านต่อ »

By clicking “Accept”, you agree to the storing of cookies on your device to enhance site navigation, analyze site usage, and assist in our marketing efforts. Privacy Policy

Privacy Preferences

คุณสามารถเลือกการตั้งค่าคุกกี้โดยเปิด/ปิด คุกกี้ในแต่ละประเภทได้ตามความต้องการ ยกเว้น คุกกี้ที่จำเป็น

Allow All
Manage Consent Preferences
  • Always Active

Save